
The Road To A Stabilized NOI – Underwriting Real Estate Concessions (Updated Nov 2026)
The incentives offered to the tenants of a real estate property constitute another of the adjustments that real estate professionals must underwrite to achieve a stabilized NOI, but beyond the adjustment, the concessions represent the cost of reaching a certain occupancy figure for the property.
Note from Arturo: This is the third post of The Road to a Stabilized NOI. This series of content intends to show the road that real estate professionals must follow to reach a Stabilized NOI, in this sense, beyond the calculations, the objective is to reflect what is behind the decisions that must be taken concerning the subscription of each one of the items that make up the proforma of a real estate property.
For example, when we are underwriting “Total Rental Income” on the pro forma of a multifamily real estate property, we begin by considering the gross potential rent, i.e., the absolute maximum we could earn if all units were occupied at market rent, then adjust that value by considering loss to leases, actual vacancy and credit loss, and finally concessions to calculate total rental income.
(+) Market Rent
(+/-) Gain/Loss to Lease
(-) Actual Vacancy & Credit Loss
(-) Concessions
(=) Total Rental Revenue
Now, on the road to a stabilized NOI, concession adjustments are synonymous with the cost of leasing and/or keeping a property occupied. While it is true that, for example, the landlord does not receive rental income during a free rent period, it is also true that they are securing a tenant for the entire duration of the lease, which ensures a stable income flow in the long term.
Concessions In Real Estate Underwriting
In the case of a lease, concessions may be synonymous with free rental periods or, for example, in a multi-family property, an agreement of the property owner that the tenant is exempt from certain charges such as pet or parking fees.
Lease agreements usually handle two terms, the first one “Lease Start” and the second one “Rent Start”, so the difference between both of them is the number of months of free rent offered.
These incentives aim to induce the tenant to sign a lease agreement, either during the initial leasing period or during tenant-favorable periods in the market cycle, to maintain rental prices.
In the following example of a proforma for a multifamily property, you can see how the market rent is adjusted in the Rental Revenue section.
Concessions can also be seen as a gesture of goodwill, which helps to build a positive relationship between the landlord and tenant from the beginning of a lease agreement, contributing to increasing the likelihood of the lease being renewed.
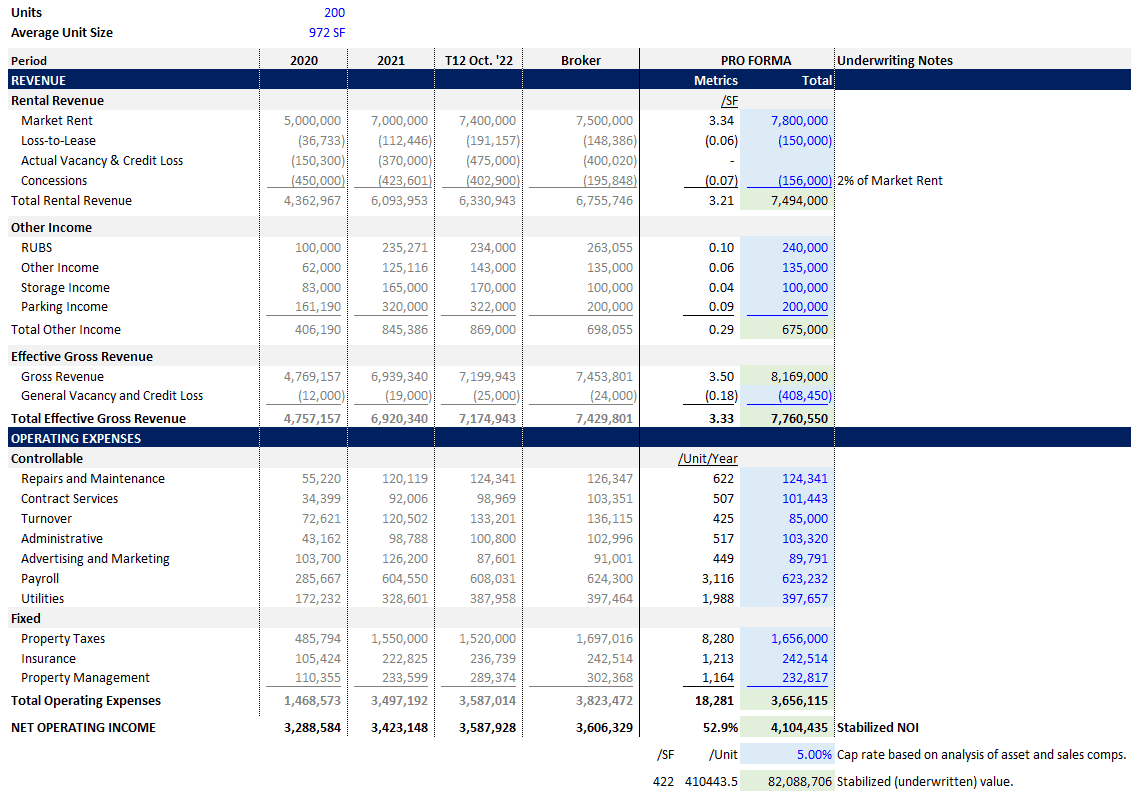
Multifamily pro forma
What sources of information should we take into account when underwriting the value of a concession in the pro forma of a real estate property?
The first thing we should review is the nature of the lease. Certainly, that will depend on the type of property. Then, just like each of the underwriting decisions, the establishment of concessions must be supported by a base that is fed from the following sources:
Internal Data: This is the first source to consult, represented by the historical data of the analyzed property and all the leases that are known directly. For example, think of companies that have a disciplined process of collecting and structuring lease information. Such companies underwrite hundreds of potential investments each year, and during that underwriting process, they gather information about the leasing conditions of tenants.
Networking: One way to enrich internal data, or if it is not available, is to turn to the contact network to obtain information about comparable leases. Brokers and property managers are a very valuable source.
External data: External data providers constitute another source of information, which provides data that is available on the market or, alternatively, data that must be purchased.
Now, the experience on the ground, along with a dynamic understanding of the market and submarket, will determine the proper management of the data provided by each of the sources.
A Look At The Concessions In Real Estate Underwriting In Properties With Short-Term Leases (Multifamily)
Multifamily properties are an example of short-term leases, which means that cash flows are less predictable. In this context, imagine that you are part of the investment team at a real estate company, and your role is to build the acquisition proforma of a multifamily property.
While in reality, the concessions are often a fixed amount per tenant (for example, X months of free rent, free parking, etc.), modeling this reality to calculate the underwritten value of concessions in the proforma will not add a worthwhile value to do so, that is why, in these cases, precision is sacrificed for the simplicity of calculating an amount that approximates the actual concessions given.
So, when you review the historical income statements (Income Statements) of the multifamily property, and you realize that the concessions are perdurable over time, in addition to reviewing the other sources described above (External data and contact network), you might come to the conclusion that, for example, a 2% adjustment of the market rent is a rational adjustment.
Beyond adjusting market rent or rental income, what’s most important is that the resulting value is consistent with the expectation of the real amount of concessions that the property offers.
However, while it is true that in some markets it is necessary to give tenants free months of rent to lease or maintain the property at a certain occupancy level, in other markets existing occupancy levels may require zero concessions.
A Look At The Concessions In Real Estate Underwriting In Properties With Long-Term Leases (Retail, Industrial, Office)
The impact that concessions have on the calculation of the stabilized NOI of a property with long-term leases is represented by periods of free rent. In this sense, the first step in underwriting a concession is to understand the terms of the lease contract.
I recommend you consult the Bite-Sized Real CRE Lessons – A.CRE 30 Second Video Tutorials and our Glossary of Terms, to clarify any doubts regarding a certain term.
Modeling the impact of concessions…
Imagine that as a real estate professional, you are working on the acquisition of a retail property with multiple existing tenants, in this sense, you would need to review or model the rent rolls of the existing long-term contracts, considering concessions for both renewal and signing a new contract.
Modeling short and long-term leases is another of the interesting topics that we cover extensively in the A.CRE Real Estate Financial Modeling Accelerator!
Therefore, in case a tenant renews, the assumptions will be very different compared to when the space is occupied by a new tenant. The most common method to analyze those two possible scenarios is to take a mix between the cost of a renewal versus the cost of a new tenant.
The reason is that for most tenants, vacating a space involves a cost, which represents the financial and logistical cost of moving to a new space. In this sense, it is usually less expensive to renew a tenant than to lease a new one.
One way to calculate the concessions related to the cost of free rent each year could be by calculating the weighted average of the concession months (renewal and contract breakage) and then multiplying it by the adjusted market rent each year. Assuming that the concessions are enduring over time, the subscription of the value in the proforma could be calculated through the average of the concessions over the years of the analysis.
In this way, we will be considering the reduction in income during free rental periods and any rent increases (Escalation) that could offset concessions on the lease terms.
Non-Permanent Concessions In Real Estate Underwriting Over Time
It is also possible that the value of the concession is not included in the proforma for a specific property. For example, imagine you are part of an investment team that is considering the acquisition of an office property of 40,000 SF, with a single tenant, who has recently signed a 15-year lease with annual rent increases of 1.5%. So, you receive the offering memorandum from the broker and decide to build your own proforma.
When you review the broker’s financial projection for the next 10 years, you notice that there is a significant cash flow from concessions present only in the first year. In this case, when you are building your own proforma to calculate the value of the property, you should not include such concession because this cash flow is not durable over time, that is, such value does not contribute to the search for a stabilized NOI.
Capturing The Risk Involved With Leasing Costs (Free Rent Periods, Tenant Improvement Allowances, Leasing Commissions) In The Acquisition Of A Real Estate Property
Imagine you are part of an investment team that is analyzing the possibility of acquiring a retail property valued at $10,000,000. This property has multiple existing tenants and vacant spaces, and the leasing costs for the vacant spaces represent a value of $1,000,000.
Assuming that the stabilized NOI is $1,000,000 and that today’s market capitalization rate is 7%, your financial model should take into account the following:
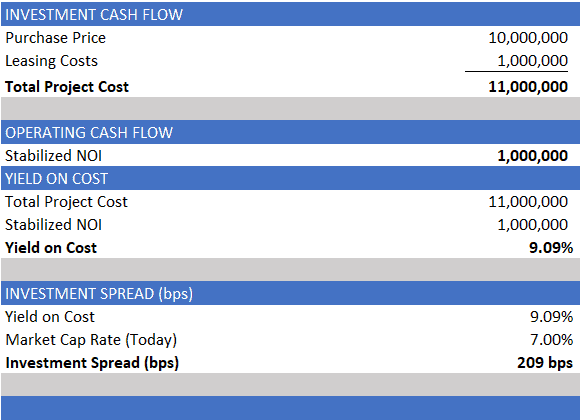
At this point, I recommend consulting the post Using Development Spread in Real Estate Analysis.
In this scenario, you can appreciate the importance of considering leasing costs in the project budget to capture the risk represented by leasing the vacant spaces. And, the stabilized NOI would be calculated once all the leases for vacant spaces are executed, and the new tenants are in place.
Final Notes
Concessions offer a range of benefits both to owners and tenants, think about those cases where tenants need time to establish their operations or renovate the space before they can start generating revenue.
On the road to a stabilized NOI, the underwriting of the concession value in a proforma also depends on the purpose of the analysis, in other words, a seller will be more aggressive in looking for a lower concession in their proforma, while a buyer will be more conservative looking for a higher concession.
While it is true that in some markets it is necessary to grant tenants months of free rent to lease or maintain the property at a certain occupancy level, in other markets it may be that the existing occupancy level requires zero concessions.
An AI Skill to Underwrite Concessions
To make that second analysis faster, I built the Concessions Underwriting Skill, the third AI Skill in The Road to a Stabilized NOI series, after the Loss to Lease Underwriting Skill and the Vacancy and Credit Loss Underwriting Skill. An AI Skill is a packaged set of instructions and tools that teaches an AI assistant to do a task the way an experienced analyst would. To learn more, check our guide to AI Skills. This one applies the methodology in this post to your deal.
What the AI Skill Does for You
- Short-term leases (multifamily): converts concession packages (free rent, reduced rent, waived fees, move-in credits) into a % of gross potential rent and calculates the net effective rent of each.
- Long-term leases (office, retail, industrial): weights free rent at each rollover between the renewal and new-tenant scenarios, at escalated market rent, and averages the cost over the hold.
Testing Durability Before Anything ElseBefore any number goes into the stabilized NOI, the Skill asks what drives the concession. Durable concessions stay in. Concessions driven by new supply stay in the direct cap pro forma and burn down in the DCF only with evidence. Lease-up and one-time concessions are carried as a cost to stabilize or a one-time item, like the single-tenant office example above.
Catching Common MistakesFace rent with no concession line. Concessions that vanish after Year 1 with no evidence. One-time free rent capitalized as if it were permanent. Lease-up free rent counted as recurring. A purchase price that ignores the leasing costs still ahead. Fee waivers deducted twice. And, above all, a concession number with no lens attached.
Framing Outputs in Your RoleA seller looks for a lower concession and a buyer for a higher one, so the Skill shows seller, neutral, and buyer lenses with the value at each. For a refinance, the lender view carries forward trailing concessions and shows the resulting DSCR and debt yield. When vacant space still needs to be leased, it adds total basis, yield on cost, and the spread to the cap rate.
Operating ContextsThe Skill runs in Claude chat and Cowork, with code execution enabled for its bundled calculator. There is no Excel file to operate, so there is nothing to recalculate.
How It Fits With the Rest of the Series
Each Skill in the series covers one deduction on the way from Market Rent to Total Rental Revenue. Loss to Lease covers occupied units paying less than today’s market rent. Vacancy and Credit Loss cover units that are empty or not paying. Concessions covers the free rent, credits, and waived fees used to sign or keep tenants. Because a property’s trailing vacancy and credit loss often already includes its concessions, the Concessions Skill hands its annual allowance to the Vacancy and Credit Loss Skill, which then leaves concessions out of its own rate. That way, each dollar of concessions shows up in your pro forma once, on its own line.
How to Use It
- Download and unzip the file, and save it to a logical place on your computer (a folder for A.CRE Skills works well).
- Add the Skill to Claude. Go to Settings > Customize > Skills, click “+”, choose “Create skill,” and upload concessions-underwriting.skill.
- Turn on code execution in the same settings area, so the bundled calculator runs the math instead of Claude estimating it.
- Try the practice case first. Open the Sierra Vista Commons case brief, start a new chat, attach the rent roll, T12, and OM excerpt, paste in the submarket table from the brief, and work through the suggested prompts.
- Run it on your own deal. Attach your T12, rent roll, or OM (or just describe the deal and the concessions being offered) and ask your question. For example: “Is the broker’s concession line in this OM supportable?”
Download The Skill
- The Skill (concessions-underwriting.skill), ready to add to your Claude account
- A README with installation steps and an overview of what the Skill does, including how it works alongside the Loss to Lease and Vacancy and Credit Loss Skills
- A practice case study, Sierra Vista Commons: a fictional 220-unit Class A community whose broker says lease-up is over and carries just $60,000 of concessions in Year 1, and nothing after that, while 1,530 new units deliver nearby. It includes a case brief with suggested prompts, the broker’s OM excerpt, a 220-unit rent roll, and a 12-month operating statement, so you can see how the Skill handles a messy, realistic deal before you trust it with yours
Read through the framework above, run the Sierra Vista Commons case, then put the Skill to work on your own deal, whether you are building the pro forma or reviewing someone else’s. It also pairs with the Loss to Lease and Vacancy and Credit Loss Skills from the first two posts in this series: give it your Vacancy and Credit Loss run, and it hands over its concession allowance so the same concession is never counted twice.
The sharpest CRE minds are already using AI to work faster, underwrite smarter, and win more deals. Join them at AI.Edge

